A repayment strategy should be understandable, affordable and connected to the actual terms of each debt. Choosing a priority is only one part of that process. Required payments, fees, changing rates and the ability to sustain the plan all matter. Do not begin with a motivational label and assume the mathematics is settled.
Make a complete debt inventory
List current balances, rates, minimum payments, due dates and any special terms privately. Distinguish secured obligations and urgent legal or housing consequences from an ordinary comparison of unsecured balances. A simple interest ranking cannot resolve every priority question.
Check the records rather than relying on memory. Promotional terms, deferred-interest arrangements and variable rates can alter the picture. Ask the creditor for clarification when a key term is missing before treating the spreadsheet as complete.
Understand the two common priorities
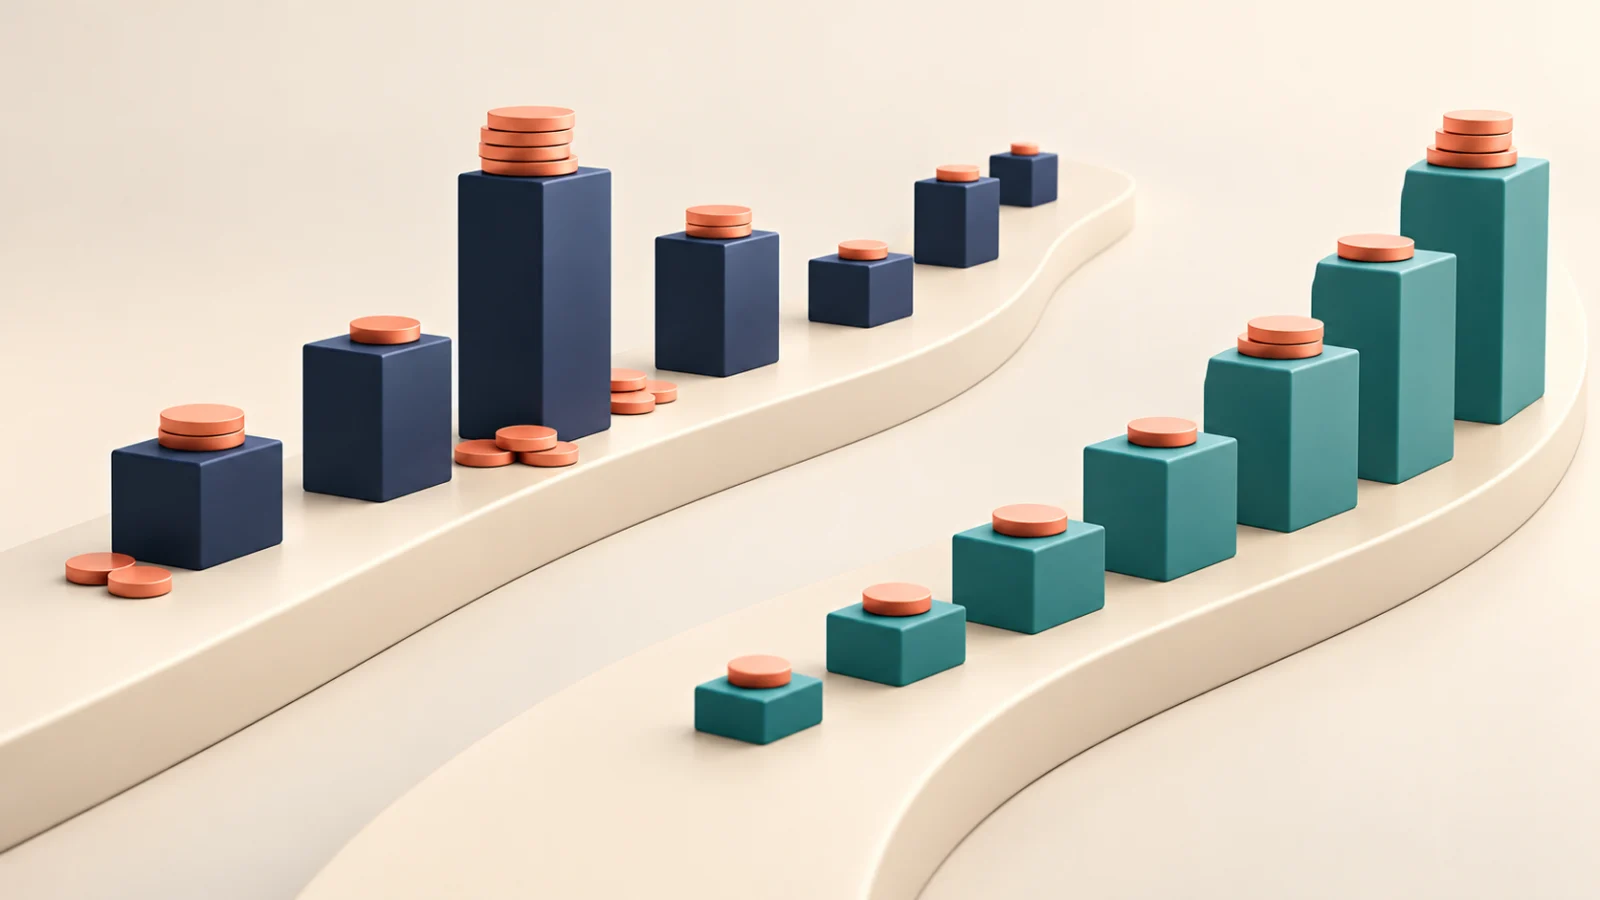
The CFPB's worksheet contrasts focusing extra payments on the highest interest rate with the snowball approach of addressing smaller balances first. One emphasizes borrowing cost; the other can provide earlier account closures and a sense of progress. The appropriate choice still depends on the whole situation.
Keep required payments on the other debts in the plan. Compare approaches using consistent total payment assumptions and actual terms. Do not claim that a chosen method guarantees motivation, avoids every fee or produces a particular credit score.
Use the right model
Everyday Altitude's Debt Payoff Comparison models one balance with a base monthly payment and an added-payment scenario. It uses a fixed entered rate and monthly interest approximation. It does not allocate payments across multiple debts or reproduce every card's billing method.
The tool rejects a payment that does not reduce the balance under its assumptions. That warning means the modeled plan cannot finish as entered; it is not a legal or account-specific determination. Fees, new charges and changing rates require separate attention.
Preserve an affordable plan
Extra payments should be evaluated alongside essential obligations and a realistic cash-flow plan. If the required payments are unaffordable, contact creditors through verified channels and evaluate qualified assistance. Credit counseling and debt settlement are different services with different implications.
Key takeaway: prioritize with accurate records, consistent assumptions and an affordable total payment. A useful model exposes tradeoffs and limitations. It should not disguise a missing term, promise a debt-free date under changing conditions or replace appropriate help when the situation is urgent.
Sources & further reading
Source review: October 29, 2026. U.S.-focused general financial education, not individualized financial, legal, tax or insurance advice. Verify current documents and applicable rules. No real offer, eligibility result, professional review or guaranteed outcome is implied.