A business can report sales while lacking cash for a bill due today. Revenue, profit and available money answer different questions. Understanding their timing helps explain why a promising order book does not automatically solve payroll, inventory or debt payments.
Trace when cash moves
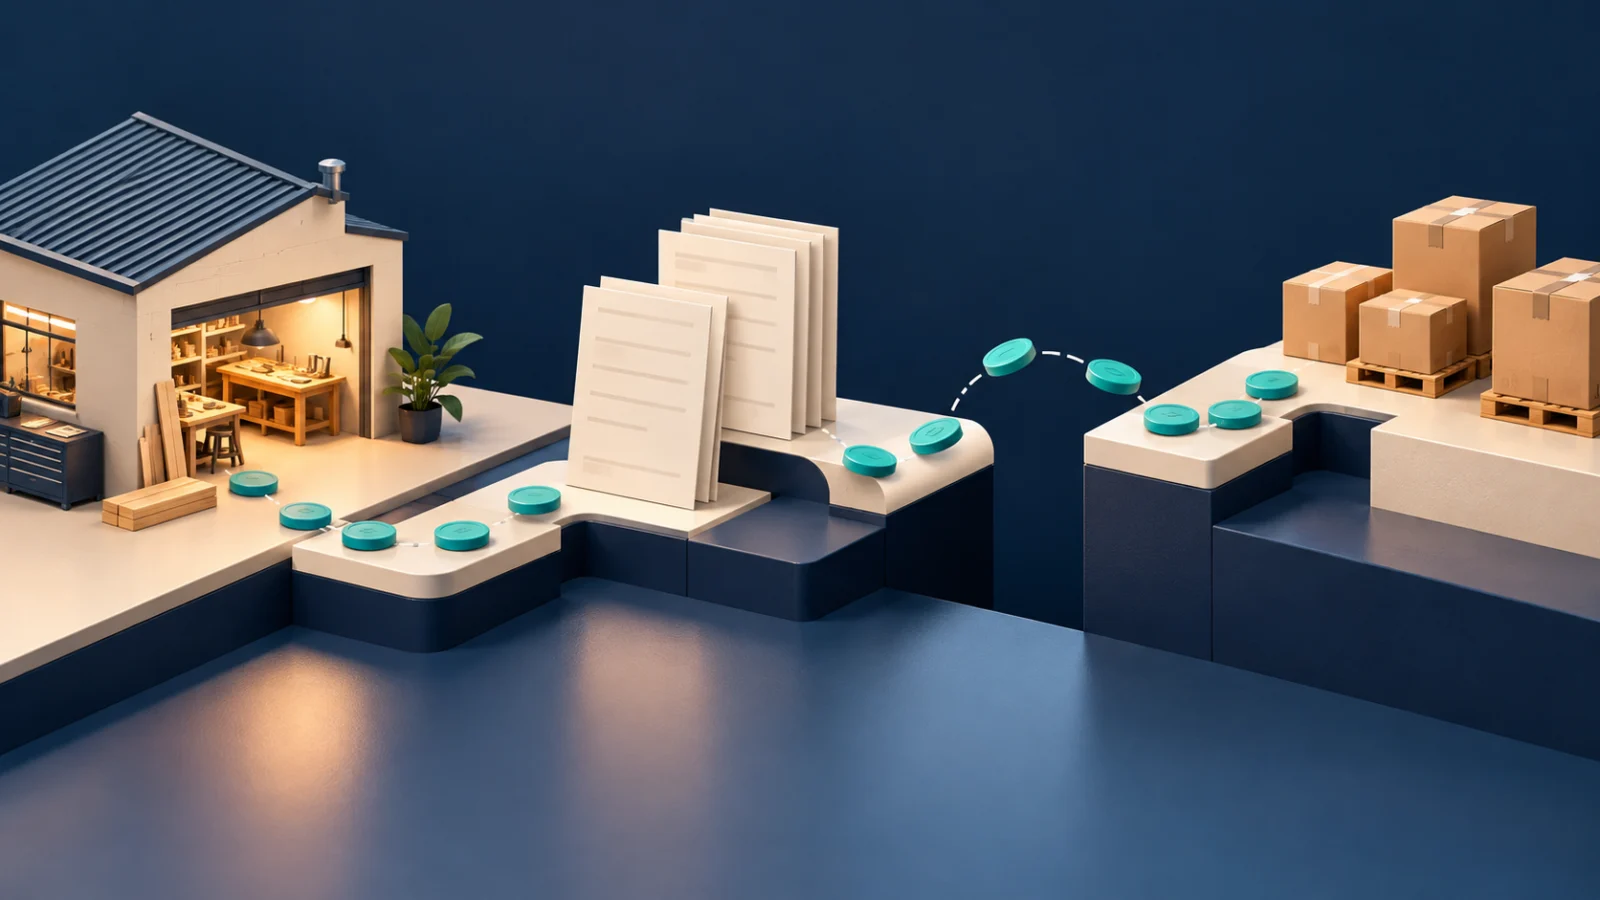
List expected receipts and required payments across relevant dates. Distinguish an invoice issued from an invoice actually paid. Customer terms, supplier schedules and other timing differences can create a gap even when the overall activity appears profitable.
Use real records where available and identify assumptions where not. An optimistic receipt date should not silently become confirmed cash. A practical forecast makes uncertainty visible so the business can examine a fallback before a deadline becomes urgent.
Separate the financial views
Profit reflects revenue and expenses under the relevant accounting method. Cash flow follows money movement. Equipment purchases, loan proceeds, principal repayments and owner transactions can affect those views differently. Qualified accounting guidance may be needed for the actual treatment.
SBA and FDIC business education emphasize financial records and cash-flow planning. Use the balance sheet, income information and cash forecast together rather than expecting one report to answer every question. A bank balance alone also does not reveal every upcoming obligation.
Examine the operating cycle
Ask how long money is committed before the associated customer payment arrives. Inventory, work in progress and receivables can each create a funding need. A growth plan may require more operating cash even before the expected profit is realized.
Do not solve a recurring gap automatically with another loan. First identify whether the problem involves timing, pricing, collection, costs or a deeper mismatch. Financing has its own cost and repayment obligations and may not correct the underlying issue.
Compare scenarios and review results
Prepare a cautious case with later receipts or lower sales and compare it with the working plan. Update the forecast when actual information changes. The point is not to predict perfectly but to see a decision early enough to investigate alternatives.
Key takeaway: cash flow is a timing and availability question that deserves its own review. Keep revenue, profit and money movement distinct. Use documented assumptions and appropriate professional help without presenting a forecast as guaranteed sales, profit or borrowing capacity.
Sources & further reading
Source review: October 29, 2026. U.S.-focused general financial education, not individualized financial, legal, tax or insurance advice. Verify current documents and applicable rules. No real offer, eligibility result, professional review or guaranteed outcome is implied.